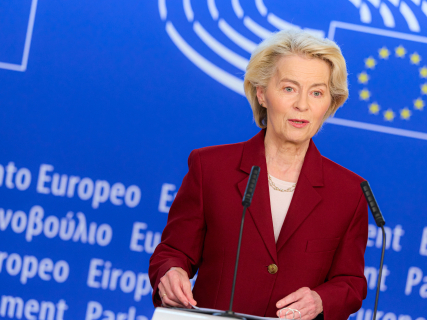
Brussels opens a case against Spain for taxing foreign pension funds more

Brussels considers that Spanish regulations establish more advantageous tax conditions for national operators in the taxation of investment income and the deduction of technical reserves, which could violate the free movement of capital in the single market

P 070784 00 01 01 ORIGINAL 234888

P 070784 00 01 01 ORIGINAL 234888

Add DEMÓCRATA to Google

Ask FREN

Published

4 minutes

Most read

Elecciones 29N · Encuestas

La media de las encuestas

Media a 19 de noviembre de 2026 · 19 institutos

  • PP31,0 %
  • PSOE27,7 %
  • Vox19,1 %
  • Frente Amplio6,2 %
  • ERC2,5 %
01020304050ene 2024jul 2024ene 2025jul 2025ene 2026jul 2026

Media del último estudio de cada instituto en 30 días y su evolución semanal desde el 23J. Partidos con al menos un 2 %.

Todas las encuestas

Elecciones generales del 29 de noviembre · Demócrata

The European Commission has opened an infringement procedure against Spain and six other Member States for applying tax rules that could impose a higher tax burden on pension funds and life insurers from other countries in the European Union. The Community Executive considers that these provisions discriminate against foreign operators compared with domestic ones and may violate the single market’s rules on the free movement of capital.

As part of its package of infringement procedures against the Member States, Brussels has sent Spain a letter of formal notice, the first formal step in a case that could end up before the Court of Justice of the European Union (CJEU). The Government now has two months to respond to the Commission’s objections and explain how it intends to correct the provisions being challenged.

A harmful tax regime for foreign operators

The Community Executive recalls that the free movement of capital is one of the fundamental freedoms of the single market. Under this principle, an entity established in a Member State must be able to invest, obtain income, or carry out its activity in another country of the Union without receiving less favorable tax treatment than that granted to a comparable domestic entity.

The problem that Brussels identifies is that certain national legislation would be providing tax advantages to pension funds and life insurers established within its own territory over foreign operators. The Commission focuses on two specific aspects: the taxation of income from investments and the deduction of technical reserves.

The latter are the financial provisions that an insurer or a fund must maintain in order to be able to meet its future obligations, such as the payment of pensions, compensation, or other commitments acquired with its customers. Their tax treatment is especially relevant for the sector, as it determines which amounts can be deducted from the taxable base before calculating the taxes that an entity must pay.

If a foreign operator cannot deduct these reserves under the same conditions as a domestic one, it ends up bearing a higher tax burden for carrying out a comparable activity. A difference that, in Brussels’ view, may discourage cross-border investment and make it harder for entities from other countries to enter the Spanish market. According to the sources consulted, the procedure does not necessarily mean that Spanish law must be invalidated as a whole. The issue is that, as certain provisions are worded, they could generate unequal treatment between domestic and foreign entities, contrary to the obligations established by Community law.

European case law has already questioned these restrictions

The Commission’s position is based on Community case law that has recognized that certain national restrictions on investments by foreign pension fund capital may violate the free movement of capital. One of the precedents is the case of Poland, whose regime was the subject of a ruling by the Court of Justice concerning the limitations imposed on external investments by open pension funds. European case law has thus established that Member States cannot use their tax rules to create unjustified obstacles to the cross-border activity of these operators.

In this context, Brussels is calling on the Spanish Government to review or amend the provisions that, according to its interpretation, fiscally harm pension funds and life insurers established in other countries of the Union when they operate in Spain.

The file is still in its first phase. The letter of formal notice opens a two-month period for Spain to submit its observations and respond to the Commission’s arguments. If the response is not satisfactory or if the necessary measures are not adopted, the Community Executive may move forward to a reasoned opinion, the next step in the infringement procedure, and eventually refer the matter to the CJEU in Luxembourg.

More competition in the capital market

Beyond the legal file, the economic consequences of a possible regulatory change could extend to the Spanish financial market. Community sources point to the fact that greater openness to foreign investment can increase competition and promote greater depth in the domestic capital market.

The entry of new European operators could expand the financing alternatives for Spanish companies and increase the volume of capital available to invest in different assets. In a market that seeks to mobilize more private savings toward the productive economy, removing tax barriers to cross-border investment is also one way to move toward greater European financial integration. However, the change could also put pressure on Spanish insurers and asset managers, which would lose part of the tax advantage they might be able to maintain over their Community competitors. Eliminating differentiated treatment would require competing under more homogeneous conditions, although the impact will depend on how each operator adapts to the new scenario.

For Spanish savers and future pensioners, the consequences would be more indirect. If domestic funds take advantage of greater freedom to diversify their investments in other European markets, they could broaden their management strategies and their possibilities of obtaining returns. However, tax openness does not itself guarantee better returns nor does it involve an automatic modification of pensions. Its effect will depend on each entity’s investment decisions and on the evolution of the markets.

More key points, information and questions with FREN

AI-GENERATED CONTENT

What is the current status of the parliamentary process for a possible tax reform to correct discrimination against foreign pension funds in Spain?

There is no record in the consulted sources of a specific tax reform currently in parliamentary process to correct this treatment of foreign pension funds. As of November 19, 2026, the identified development is the opening of an infringement procedure by the European Commission against Spain, still in its initial phase. Therefore, a distinction must be made between the European request to the Government and a legislative reform presented before the Cortes.

The current point: a European request, not a law pending vote

According to Demócrata on November 19, Brussels has sent Spain a letter of formal notice: the communication that formally opens the infringement procedure. The Commission considers that certain tax rules could impose a higher burden on pension funds and life insurers from other Member States compared to comparable national entities.

The Government has two months to respond to the objections and explain its position or the measures it intends to take to correct them. This deadline corresponds to the response to Brussels: it is not a parliamentary deadline to approve a law nor a date for the entry into force of a tax modification.

If the Spanish response is unsatisfactory, the Commission may issue a reasoned opinion, a subsequent formal request to correct the non-compliance. Eventually, it could take the matter to the Court of Justice of the European Union. These steps are subsequent and should not be presented as decisions already made.

What the eventual reform would have to correct

The published information places the problem in two areas: taxation of investment income and deduction of technical reserves. These reserves are amounts that entities provision to meet future obligations, such as payment of pensions or insured benefits.

The European objection is that if a foreign entity cannot deduct these amounts under conditions equivalent to a comparable national entity, it may end up bearing a higher tax burden. Brussels understands that such treatment could restrict the free movement of capital. Therefore, this is not a proposal to modify public pensions or individual contributions to pension plans.

What is known about its parliamentary progress

In the consulted sources, no bill or legislative proposal with this specific purpose has been identified, nor an amendment text that would place the correction in committee, commission, Plenary, or Senate. Nor has a final approval and publication of such reform been located. The conclusion must be limited to this: there is no concrete parliamentary progress accredited that can be described as advanced or close to completion.

It is advisable not to confuse this matter with other actions on cross-border pensions. In October 2025, Demócrata reported a prior consultation to allow contributions exceeding the deductible maximum and facilitate transfers between plans from different EU countries. That action addressed barriers to worker mobility and savings, and does not evidence a parliamentary reform on the now questioned tax discrimination.

Practical conclusion

The situation is, for now, a Government response to the European procedure, not parliamentary approval of an identified solution. The opening of the procedure does not automatically change the tax obligations of the affected funds. The next relevant milestones will be the Spanish response, the possible publication of a regulatory proposal, and, if legal changes are required, its presentation and processing in the Cortes. No committed parliamentary timetable for this correction is recorded.

What are the competencies of the Court of Justice of the European Union regarding infringement procedures against Member States?

The Court of Justice of the European Union (CJEU) is the judicial body that ultimately decides whether a Member State has failed to fulfill its obligations under EU law. In matters of infringement procedures, its role is strictly judicial: to establish non-compliance, interpret the applicable law, and, where appropriate, impose or confirm financial sanctions.

1. General framework of the infringement procedure

The infringement procedure is mainly regulated in Articles 258 to 260 of the TFEU. It has two phases:

  • Pre-litigation (administrative) phase, led by the European Commission: letter of formal notice, reasoned opinion, and attempts at amicable settlement.
  • Contentious phase, before the CJEU: begins when the Commission (or, exceptionally, another Member State) brings an action against the allegedly infringing State.

The CJEU does not initiate infringement procedures on its own nor investigate States; it only hears cases brought by authorized bodies (mainly the Commission).

2. Main competencies of the CJEU in these procedures

a) Hearing infringement actions (Art. 258 TFEU)

The essential competence of the CJEU is to resolve infringement actions brought:

  • Usually by the European Commission, after the pre-litigation phase, when it considers that a State has breached Union law (for example, failing to transpose a directive, misapplying it, violating a fundamental freedom, or circumventing a regulation).
  • Exceptionally, by another Member State (Art. 259 TFEU), although this mechanism is much less used.

The CJEU analyzes the situation in light of EU law (treaties, regulations, directives, general principles, case law) and issues a declaratory judgment in which:

  • It determines whether the State has failed to fulfill its obligations.
  • It specifies the scope of the infringed obligations, setting binding legal interpretation criteria for all States and institutions.
b) Declaring the existence of non-compliance

The central function of the CJEU is to legally establish the non-compliance. If it finds an infringement, the judgment:

  • Declares that the Member State “has failed to fulfill the obligations incumbent upon it under the Treaties.”
  • Requires the State to take “the necessary measures” to comply with the ruling, which may involve reforming laws, repealing rules, modifying administrative practices, or adopting implementing acts.

This declaration carries significant political and legal weight and serves as a reference in other national and European litigations.

c) Imposing financial sanctions (Art. 260 TFEU)

The CJEU also has a sanctioning competence in case of persistent non-compliance:

  • If, after a first condemnatory judgment, the Commission finds that the State has not complied, it may bring the matter back to the CJEU requesting the imposition of a lump sum (fixed fine) and/or a daily or periodic penalty payment.
  • Since the Lisbon Treaty, in cases of failure to notify transposition measures of certain directives, the Commission may request sanctions already in the first referral to the Court.

The CJEU decides whether to impose sanctions and sets their amount, considering the seriousness of the infringement, its duration, and the economic capacity of the Member State.

d) Ancillary procedural competencies

Besides declaring non-compliance and, if applicable, sanctioning it, the CJEU exercises several procedural competencies:

  • Interpretation of EU law: when resolving the case, the Court may clarify the meaning of European norms, which has effects beyond the specific litigation.
  • Assessment of evidence and arguments: decides on the sufficiency of proof by the Commission or the State, relevant deadlines, existence of justifications alleged by the State, etc.
  • Interim measures (in very exceptional cases): may adopt precautionary measures to avoid serious and irreparable harm to the Union’s interest while deciding on the merits.
  • Review and appeal control: its judgments in infringement procedures are, in practice, final within the EU judicial system.

3. Limits of its role in infringements

The CJEU does not replace the State in choosing the specific means to comply with the judgment: it only declares the infringement and, if applicable, sets sanctions. It is up to the State to decide how to adapt its internal legal order. It also does not investigate facts on its own or act ex officio: it depends on the initiative of the Commission or a Member State to open a procedure.

In summary, regarding infringement procedures, the CJEU is the ultimate guarantor of respect for Union law by Member States: it legally declares non-compliance, sets interpretation criteria, and, when necessary, supports the effectiveness of its rulings through financial penalties.

What legal requirements must Spain meet to adapt its tax legislation to European regulations on the free movement of capital?

Spain must ensure that its taxes do not discriminate against or unjustifiably restrict cross-border investments. Adapting its legislation does not mean equalizing all its taxes to those of other countries, but exercising its fiscal competence while respecting the free movement of capital, the admitted exceptions, and taxpayers’ guarantees.

1. Respect the prohibition of restrictions

The starting point is Article 63 of the Treaty on the Functioning of the European Union (TFEU), which prohibits restrictions on capital movements and payments between Member States and, as a general rule, also with third countries. The treaty framework was reformed by the Lisbon Treaty.

Spain must review both express discriminations and measures that, without distinguishing by nationality, make investing outside Spain or receiving foreign capital less attractive. This affects, for example, the treatment of dividends, interest, real estate investments, cross-border inheritances, and donations.

2. Compare equivalent situations

Not every difference between residents and non-residents is prohibited. Article 65 of the TFEU allows certain tax distinctions linked to residence or place of investment but does not authorize arbitrary discrimination or disguised restrictions.

The assessment must be made considering the objective of each tax. If two taxpayers are in objectively comparable situations regarding that objective, Spain cannot impose a higher burden on the cross-border element without justification. The full effective taxation must be examined: rates, deductions, exemptions, withholdings, deductible expenses, and refund possibilities, not just the nominal percentage.

3. Justify restrictions and demonstrate proportionality

When a measure limits capital movement, it must respond to a justification accepted by European law. Possible reasons include effective tax control and combating fraud; invoking them generically is insufficient.

  • Suitability: the measure must genuinely serve the declared objective.
  • Necessity: there must be no equally effective and less restrictive alternative.
  • Proportionality: its burdens, documentary requirements, and sanctions cannot exceed what is necessary.

Therefore, it cannot be automatically presumed that all foreign investment is fraudulent. Information exchange mechanisms and possibilities to provide evidence must be assessed. In relations with third countries, the analysis may vary due to treaty exceptions and available cooperation.

4. Properly adapt rules and their application

Reforms must be approved through the appropriate legal instrument. When modifying tax elements reserved to law, an administrative circular or a change in criteria is insufficient. Regulations, forms, and practices that maintain an incompatible restriction must also be reviewed.

Additionally, Spain must correctly and timely incorporate applicable tax directives. Complying with a directive does not eliminate the obligation to respect the Treaty in aspects not harmonized by it. This requirement applies to all Spanish administrations, including autonomous communities when exercising tax powers.

5. Guarantee remedies and correct non-compliance

The primacy of Union law requires leaving incompatible national provisions unenforced when appropriate. Taxpayers must have effective means to challenge assessments and request refunds of payments contrary to European law, with corresponding interest and respecting applicable procedural rules.

In short, adaptation requires reviewing, justifying, and correcting: identifying cross-border disadvantages, checking if they affect comparable situations, and eliminating those that do not pass the proportionality test. Identical taxation is not required, but taxation compatible with European freedoms is.

Play

Test your knowledge with FREN!

How much do you know about this topic? Answer the following 3 questions.

What action has the European Commission taken against Spain regarding the taxation of foreign pension funds?

Question 1 of 3

What deadline does Spain have to respond to the formal notice letter sent by Brussels?

Question 2 of 3

What is one of the economic consequences that could result from removing tax barriers for foreign operators in the Spanish market?

Question 3 of 3