AIReF raises GDP growth, worsens the deficit, and warns that Spain will not meet the plan agreed with the EU

AIReF improves GDP growth, but worsens the deficit and warns that Spain will not meet the fiscal plan agreed with Brussels.

fotonoticia 20261104130640 1920

fotonoticia 20261104130640 1920

Add DEMÓCRATA to Google

Ask FREN

Published

Last updated

4 minutes

Most read

Elecciones 29N · Encuestas

La media de las encuestas

Media a 4 de noviembre de 2026 · 15 institutos

  • PP31,0 %
  • PSOE26,3 %
  • Vox19,5 %
  • Frente Amplio6,5 %
  • ERC2,5 %
  • Podemos2,2 %
  • SALF2,2 %
01020304050ene 2024jul 2024ene 2025jul 2025ene 2026jul 2026

Media del último estudio de cada instituto en 30 días y su evolución semanal desde el 23J. Partidos con al menos un 2 %.

Todas las encuestas

Elecciones generales del 29 de noviembre · Demócrata

The Independent Authority for Fiscal Responsibility (AIReF) has slightly raised its growth projections for the Gross Domestic Product (GDP) of Spain for 2026 and 2027, to 2.6% and 2.2%, respectively, but at the same time has warned of a deterioration in the public deficit scenario and the failure to comply with the fiscal plan committed to the European Union.

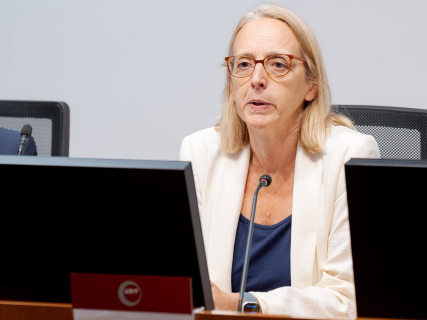
The independent body headed by Inés Olóndriz has made public this Wednesday the report on the projects and the basic lines of the Budgets of the Public Administrations for 2027, a document in which it updates its macroeconomic framework and its fiscal forecasts.

The chairwoman of the AIReF has acknowledged in a press conference that the lack of a General State Budgets project and of a draft Budget Plan again narrows the scope and precision of its analysis.

In a scenario of constant policies, the AIReF expects that deviations in net primary expenditure from revenue-raising measures will exceed the margins of the new fiscal framework agreed with Brussels from 2026 and throughout the entire period of application of the Plan, even applying the maximum flexibility provided.

In detail, the body calculates average growth in net primary expenditure of 5.7% between 2026 and 2028, clearly above the 3.2% committed by the Government to the European Union. For the AIReF, these differences will require adopting additional measures if the European commitments are to be respected.

On the macroeconomic front, the improvement in the AIReF’s expectations for GDP in 2026 and 2027, to 2.6% and 2.2%, respectively, is explained above all by the better performance of activity in the second quarter of 2026 and by the carryover effect on 2027. In any case, the institution projects a gradual slowdown in growth in the medium term, to 1.7% in 2031.

In addition, the body expects inflation to rise by 3.6% in 2026 and 3% in 2027, which represents three and six tenths more, respectively, than in its previous scenario.

In the area of public accounts, the AIReF has raised its deficit forecast to 2.8% of GDP in 2026 due to the impact of the new energy measures adopted to mitigate the consequences of the conflict in the Middle East. For 2027, it estimates that the deficit will fall to 2.6% with the withdrawal of these temporary actions.

However, the institution underlines that this correction will be conditioned by the increase in structural spending. Under the assumption of constant policies, the deficit would return to 2.8% of GDP in 2028 and would continue to rise to 3% in 2031, driven by the higher cost associated with population ageing, the interest on the debt, and the commitments in defense matters.

Public revenues, without considering the Recovery, Transformation and Resilience Plan (PRTR), would rise from 42.4% of GDP in 2026 to 43.3% in 2031, supported mainly by the collection of the IRPF and social security contributions. In parallel, total spending would increase from 45.2% to 46.4% of GDP over that same period, pressured by demographic ageing, defense obligations, and the increase in the cost of debt, whose interest spending would reach 3.2% of GDP in 2031.

Behavior by subsectors and tone of fiscal policy

By subsectors, the AIReF expects that all of them, except Local Corporations (CCLL), will show between 2026 and 2028 an average growth in net primary spending on income-measure revenues above the target set in the PFEMP. The Central Administration leads the increase, with an average rate of 8.3%, followed by the Autonomous Communities (CCAA), with 5.2%, and the Social Security Funds, with 4.8%, while the CCLL would be at 3.2%.

As for the balance, the bulk of the public deficit will be concentrated in the Central Administration, which would reach 3.3% of GDP in 2031. The Social Security Funds would maintain a stable deficit of around 0.1% of GDP, the CCAA would move close to balance, though with disparities between regions, and the CCLL would preserve a surplus close to 0.3% of GDP.

In 2026, fiscal policy would adopt an expansionary bias equivalent to 1.3 percentage points of GDP, in a context in which the economy will operate above its potential level, setting a procyclical tone contrary to that established by the Government in the PFEMP. In addition, the adjusted public balance for the cycle and for specific measures would remain around -3% of GDP, with deterioration in 2026.

Public debt and risks to sustainability

The AIReF projects that the ratio of public debt will continue on a downward path until it reaches 95.4% of GDP in 2031, supported by the positive contribution of the economy’s nominal growth. However, it warns that this momentum will gradually lose strength as the weight of interest increases in an environment of more demanding financing conditions.

The planned trajectory has been slightly revised upward compared with the May report, and sensitivity analyses indicate that a less favorable pattern of growth or the primary balance could end up slowing the reduction in debt.

AIReF recommendations to the Ministry of Finance and to regional administrations

In view of the lack of a draft of the General State Budgets and of a draft Budgetary Plan, the AIReF urges the Ministry of Finance to set in motion the work needed to design a medium-term fiscal strategy that includes the necessary measures to achieve a path of net expenditure growth compatible with the commitments made with the European Union.

At the same time, it recommends that the Ministry of Finance, the CCAA and the CCLL with a risk of deviation avoid approving new decisions that involve structural increases in net primary expenditure. This affects both permanent reductions in revenues and increases in spending that do not have assured structural financing.

The institution emphasizes that respect for the fiscal rules should serve to strengthen the sustainability of public accounts and reduce the vulnerability derived from maintaining a volume of debt close to 100% of GDP, especially in a context of higher interest rates and more demanding financing.

More key points, information and questions with FREN

AI-GENERATED CONTENT

What is the processing status of Spain's Budgetary Plan before the European Union and what are the next steps required for its approval?

As of November 4, 2026, the Spanish annual Budgetary Plan for the next fiscal year has not been submitted to the European Commission according to the sources consulted. The information published today about AIReF's report for 2027 specifically points out the absence of a draft Budgetary Plan. Therefore, it is not only pending final European approval: its submission is missing to complete the ordinary evaluation.

It is important to distinguish this annual document from the Medium-Term Fiscal-Structural Plan 2025-2028, whose path was already endorsed by the EU Council on January 21, 2025. Additionally, the EU supervises the annual plan but does not approve the General State Budgets: that approval corresponds to the Spanish Parliament.

Current status and background

The most recent reference is the information from Demócrata about AIReF, published on November 4: the lack of a draft General State Budget and Budgetary Plan limits the analysis of the scenario for 2027. The sources consulted also do not show a specific opinion from the Commission on this annual document.

The delay has precedents. The Eurogroup, on December 11, 2025, confirmed that Spain had not yet submitted the plan corresponding to 2026 and requested its submission as soon as possible. That statement refers to the previous cycle and does not by itself confirm the situation for 2027.

In parallel, multiannual supervision continues. The Council of Ministers approved on April 28, 2026 the submission of the Annual Progress Report. This monitoring does not replace the annual Budgetary Plan.

Next required steps
  • Submission by Spain. The Government must submit the Draft Budgetary Plan with its fiscal forecasts and measures for the following fiscal year. The ordinary calendar establishes its submission before October 15 and before approving the national budget. For the 2027 cycle, that deadline has already passed.
  • Opinion of the European Commission. Brussels must assess the consistency of the document with European recommendations and the net expenditure path of the Council. The ordinary deadline to issue the opinion is November 30; this should not be interpreted as a guaranteed approval date for a document not yet submitted. The Commission explains the framework on its fiscal surveillance of Spain page.
  • Examination by the Eurogroup. The Ministers of Economy and Finance of the euro area discuss the opinion. The Eurogroup itself indicated it would evaluate the Spanish plan when the document and the Commission's opinion were available.
  • National adaptation and European monitoring. The Government and Parliament must consider the European observations and, when appropriate, adopt measures to comply with the Council's recommendation. This is described by the Commission in its explanations of the European Semester. ECOFIN can adopt recommendations or supervisory decisions, but there is no approval of the Spanish budgets by this body.
What is approved and what is missing

The endorsed multiannual path contemplates maximum net expenditure growths of 3.7% in 2025, 3.5% in 2026, 3.2% in 2027, and 3.0% in 2028. The annual plan must be consistent with this framework and applicable flexibilities.

In conclusion, the next decisive milestone is to submit the annual document; then will come the Commission's opinion, the Eurogroup's examination, and the necessary adaptations. There is no missing European vote that converts the plan into Spanish budget law.

What are the functions and powers of the president of AIReF according to Spanish legislation?

The president of AIReF leads and legally represents the body, coordinates its organs, and exercises the senior management of its staff. Their powers are mainly regulated in Organic Law 6/2013, especially in articles 24 and 25, and are developed in the Organic Statute, approved by Royal Decree 215/2014, particularly in article 25.

1. Direction, representation, and independence

The Presidency exercises its functions "with full independence and objectivity, without being subject to any instruction." It cannot request or accept instructions from public or private entities; AIReF's attachment to the Ministry of Finance does not eliminate that independence.

  • Legally represents AIReF and directs and coordinates its governing bodies.
  • Convenes and chairs the Steering Committee and decides on the attendance of staff or external experts.
  • Leads international relations, in coordination with the Ministry of Finance.
  • Signs agreements with public and private entities within the body's competencies.
2. Reports, studies, and planning

They are responsible for signing AIReF's reports, opinions, and studies. They also agree on conducting requested studies, respecting the cases in which the law requires them to be prepared: they do not have unlimited power to reject them.

They approve the Action Plan and the annual report, after deliberation by the Steering Committee. These responsibilities serve the institutional mission of evaluating the budget cycle, public debt, and economic forecasts. The reports are not binding, but the recipient Administration must justify any departure from their recommendations.

3. Information and duty of cooperation

They may require information from public sector entities and approve official lists of information necessary for the reports. They decide to publish warnings when the duty of cooperation is breached. Additionally, they assess whether the breach is serious or repeated and agree on its publicity and communication to the Government, the Parliament, and the non-compliant Administration. This power does not equate to imposing legal measures against non-compliance by themselves.

4. Personnel and organization
  • Proposes to the Council of Ministers the appointment and dismissal of division directors; does not appoint them directly.
  • Agrees on the appointment and dismissal of the remaining staff, calls and resolves selection and provision procedures, and signs employment contracts.
  • Proposes the job positions list and redistributes staff among divisions according to service needs.
  • Proposes amendments to the Statute and informs the Ministry of Finance about convenient changes in the organizational structure.
5. Budget, contracting, and assets

Approves the draft budget and submits it to the Ministry of Finance to be integrated into the General State Budgets. Authorizes expenses, orders payments, and agrees on budget modifications within its limits: certain variations, especially those related to personnel or state contributions, require other authorizations.

Also, they prepare, approve, and render accounts. They are the contracting authority and may delegate this power only for contracts with an estimated value below 120,000 euros. They manage assets, agree on acquisitions, uses, and leases of real estate, and approve the inventory.

6. Accountability and delegation

They appear at least annually before the competent committees of the Congress and the Senate. They participate, with voice but no vote, in the Fiscal and Financial Policy Council, the National Local Administration Commission, and the Social Security Financial Commission.

Since the reform of Royal Decree 1061/2025, they approve the system for selecting independent external evaluators, after deliberation by the Steering Committee. The evaluation must be carried out at least every six years.

They may delegate functions to division directors, except parliamentary appearances, the proposal of appointment and dismissal of those directors, and the preparation, approval, and rendering of accounts.

What requirements must public administrations in Spain meet to be able to increase structural expenditure according to the current fiscal framework?

Public administrations can increase structural expenditure —that which generates permanent commitments— if the increase is compatible with spending rules, stability and debt targets, and financial sustainability. Having money this year is not enough: they must assess future costs and prove they can sustain it without breaching the Spanish framework or European commitments.

1. Respect the national spending rule

Article 12 of Organic Law 2/2012 limits the growth of computable spending by the central administration, autonomous communities, and local corporations to the medium-term GDP reference rate. For 2026, the reference is 3.5%, according to the guidelines from the Ministry of Finance.

The limit does not apply to the entire budget: it excludes, among other concepts, interest, non-discretionary unemployment spending, spending financed with earmarked European or other administrations' funds, and certain transfers from financing systems. Social Security is not included in this national rule of article 12, although it is subject to other stability and sustainability requirements.

2. Distinguish permanent revenues from cyclical collection

To expand the ordinary limit, article 12.4 establishes a specific authorization: when regulatory changes generate permanent increases in revenue, computable spending may increase "by the equivalent amount" in the years those revenues are obtained. If regulatory changes reduce revenue, the limit must decrease by the corresponding amount.

Therefore, not every increase requires a tax hike: it may fit within the ordinary margin or be offset by savings in other items. But higher-than-expected revenue does not automatically expand that margin: article 12.5 stipulates that such income must be fully allocated to reducing public debt.

3. Also comply with the European path

The European framework, reformed in 2024, supervises net primary expenditure excluding revenue measures: an adjusted magnitude that discounts interest and other components. Spain must respect the trajectory of the Fiscal and Structural Plan; for 2026, the committed rate is 3.5%.

The national and European magnitudes are not identical, nor are they applied with the same scope: the European supervises the entire set of administrations. Complying with one does not guarantee compliance with the other, as AIReF has warned and Demócrata reports. European deviation margins also do not constitute a general authorization to create permanent spending.

4. Preserve stability and finance future commitments

Article 135 of the Constitution and Organic Law 2/2012 require respecting budgetary stability. The increase must fit within applicable deficit and debt targets; local entities must maintain balance or surplus, and Social Security has its specific regime.

Additionally, the present and future impacts of the measure must be evaluated, incorporated into multiannual planning, and financing compatible with fiscal limits and payment to suppliers must be guaranteed. Approving a budget item alone is not enough to prove that sustainability.

5. Attend to corrective plans and exceptions

If there are imbalances or breaches, growth must adjust to the corresponding economic-financial or rebalancing plans. Exceptions for catastrophes, recessions, or extraordinary emergencies require the established procedures; in the constitutional sphere, an absolute majority in Congress. These are temporary and conditional deviations, not a permanent waiver.

In summary: spending margin, sustainable financing, compatibility with both rules, and multiannual budget fit are needed. Having extraordinary revenues or only meeting the deficit target is not enough.

Play

Test your knowledge with FREN!

How much do you know about this topic? Answer the following 3 questions.

What is the GDP growth forecast for Spain in 2026 according to AIReF?

Question 1 of 3

What recommendations does AIReF make to the Ministry of Finance and territorial administrations regarding sustainability risks?

Question 2 of 3

To what is the improvement in GDP growth expectations for 2026 and 2027 mainly attributed according to AIReF?

Question 3 of 3