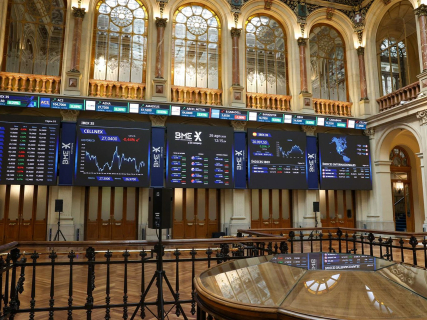

The Ibex 35 closed this Thursday with a 1% increase, up to 19,831.8 points, expanding the advance of 0.48% it recorded at the opening and recovering a good part of the ground lost during the last sessions.
The rebound came after the Federal Reserve of the United States decided, with the European stock markets already closed on Wednesday, to raise interest rates by 25 basis points. The decision represents the first tightening move under the leadership of Kevin Warsh at the head of the institution.
The Fed raises rates despite Trump's pressures
The Federal Reserve has chosen to increase the cost of money at a time marked by persistent inflationary pressures and the high cost of energy.
The decision contrasts with the position defended by the U.S. president, Donald Trump, who advocates lowering rates just a month and a half before the midterm elections.
The market will now remain especially attentive to the next signals from the Fed to determine whether this increase represents an isolated move or the beginning of a new period of monetary tightening.
The Bank of England keeps rates at 3.75%
The day has also left a new monetary decision in Europe.
The Bank of England has kept its official rate unchanged at 3.75%, considering that there are still no clear signs of second-round effects on prices.
The British institution continues, however, to monitor the risks arising from the increase in energy costs, one of the factors that is most conditioning inflation prospects.
Santander, Mapfre, and Aena lead the rebound
The advance of the Ibex has had the support of several of its most significant values.
Mapfre has led the gains with an increase of 2.62%, followed by Banco Santander (+2.06%), Aena (+2%), Repsol (+1.95%), Solaria (+1.92%), and Endesa (+1.91%).
The advance of Santander has particularly contributed to the behavior of the selective due to the weight of the entity within the index.
Repsol has also managed to close with strong gains despite the correction recorded this Thursday in the price of oil.
Cellnex and Inditex miss out on the increases
On the opposite side, Cellnex recorded the largest drop in the Ibex, with a decrease of 1.45%.
Inditex (-0.72%), CaixaBank (-0.57%), Sacyr (-0.57%), and Ferrovial (-0.56%) also ended in negative territory.
The day has thus left an uneven evolution within the Spanish market, although the overall balance has been clearly positive and has allowed the selective index to return to the zone of 19,800 points.
Eurozone inflation rises to 3.2%
Monetary policy is once again gaining prominence at a time when European inflation continues above the European Central Bank's target.
Eurostat confirmed this Thursday that the inflation of the eurozone increased in August to 3.2%, compared to the 2.9% recorded in July.
The definitive figure is, however, one-tenth below the preliminary estimate published at the beginning of the month.
The persistence of price pressures keeps attention open on the upcoming decisions of the ECB, after the recent rate hike agreed by the institution.
The Treasury pays more to place debt
In Spain, the Public Treasury has placed 5,740.3 million euros in a medium and long-term debt auction.
The figure has been situated in the central part of the expected range, although the State has had to raise the yield offered to investors above 3.5% in the three issued references.
The evolution reflects the new scenario of high rates and greater yields demanded in the fixed income markets.
Trump threatens with new tariffs on the EU
To the monetary uncertainty is added the trade front.
Analysts from Renta 4 have warned that Trump threatens to impose new tariffs on the European Union after the invitation to Canada to become an associated member of the community bloc.
According to the firm, the U.S. president has even raised the possibility of reducing part of the trade with Europe.
Trade policy thus becomes another risk factor for markets already conditioned by inflation, interest rates, and geopolitical tension.
Oil falls but remains above 100 dollars
After the strong increases accumulated during the last weeks, oil has corrected this Thursday.
The Brent has dropped by 2.08%, to 103.63 dollars per barrel, while West Texas Intermediate has retreated by 1.16%, to 101.23 dollars.
The drop offers some relief after a surge that had placed crude at particularly high levels, although both references continue clearly above 100 dollars.
Europe accompanies the gains of the Ibex
The positive tone has spread to the rest of the main European markets.
London has risen by 1.19%, Milan by 0.80%, Frankfurt by 0.70%, and Paris by 0.57%.
In fixed income, the yield of the Spanish ten-year bond has decreased to 3.942%, compared to 3.967% on Wednesday.
The risk premium has stood at 46.3 basis points.
The euro, for its part, has appreciated by 0.11% against the dollar, to 1.1465 dollars per euro.