Citi and JP Morgan see a limited impact of the elections on the economy and highlight the role of immigration in growth.

The two investment banks expect a limited short-term effect and point out the growth of the labor force, housing, and legislative capacity as decisive variables.

4 minutes

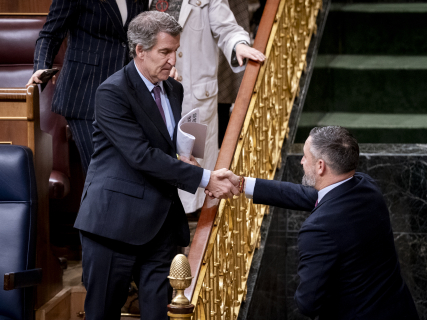
EuropaPress 7280799 presidente partido popular alberto nunez feijoo saluda presidente vox

EuropaPress 7280799 presidente partido popular alberto nunez feijoo saluda presidente vox

Add DEMÓCRATA to Google

Ask FREN

Published

Last updated

4 minutes

Most read

The advance of the general elections to November 29 does not, by itself, represent an immediate blow to the Spanish economy. The analyses prepared by Citi and JP Morgan after the announcement point out that the impact in the very short term will be limited and focus attention on what happens after the polls: the ability of the next Government to legislate, the policies on housing and immigration, and the regulatory framework that affects companies and banks.

JP Morgan considers that the early elections will have "limited repercussions on the economic outlook in the very short term." The entity points out that the macroeconomic data and the growth drivers that are already functioning will carry more weight than the electoral announcement itself.

Citi reaches a similar conclusion regarding the short term. Its analysis also does not expect relevant immediate consequences on activity, although it identifies several areas where a political change could have medium-term effects. Among them are banking, housing, and population evolution.

Citi points to banking, housing, and immigration

Citi's analysis focuses on other effects that a political change could produce. The entity considers that a hypothetical Government led by the PP could be perceived by investors as more favorable to banking consolidation and a more favorable fiscal framework for the sector.

Citi recalls that the current Government previously opposed BBVA's takeover bid for Sabadell and suggests that a PP Executive that did not depend on Catalan independentist parties could have a different position regarding the consolidation of the banking sector. The entity also analyzes the future of the special tax on banking and the consequences that a change of Government could have on the roadmap for state participation in CaixaBank. 

But banking is not the only area that Citi identifies as relevant. Its analysis places housing and immigration alongside economic policy among the issues that will concentrate the electoral debate. For the entity, the changes that may occur in the medium term both in population growth and in housing demand could ultimately have effects on the growth of deposits and loans.

The housing appears thus connected with two different economic variables. On one hand, it constitutes one of the main political issues of the campaign. On the other, its evolution affects the demand for financing and, therefore, a part of the banking business that Citi analyzes in its report.

JP Morgan puts immigration at the center of growth

The element that acquires special relevance in JP Morgan's analysis is immigration. The entity considers that the expansion of the active population driven by the arrival of foreign workers is one of the engines that are sustaining the growth of the Spanish economy.

The investment bank points out that this factor, along with the investment financed by the Next Generation EU funds, may have enough weight to eclipse the aggregate effect that political uncertainty has on activity. That is to say, the electoral call does not appear as the main conditioning factor for growth in the short term.

This reading introduces a relevant variable in the electoral debate. Decisions about immigration do not only affect the demographic or labor sphere: for JP Morgan, they also have a direct relationship with the growth capacity of the Spanish economy through the active population.

The analysis adds that political fragmentation and the "regulatory inertia" of recent years may have hindered private investment. At this point, the holding of elections may have an effect different from the purely electoral: the subsequent formation of a Government with a parliamentary majority could reduce uncertainty about its ability to pass laws.

The challenge lies in the policies that come after the polls

The two analyses therefore agree in separating the immediate effect of the elections from their possible subsequent consequences. The call for November 29 does not change by itself the engines that are sustaining activity, but the result may determine the framework in which economic policies will be developed during the next legislature.

For JP Morgan, one of the decisive elements will be that the next Executive achieves sufficient legislative capacity to reduce the uncertainty that has accompanied parliamentary fragmentation. The entity links that capacity with the prospects for private investment and with the possibility of advancing new measures.

In parallel, the analysis from Citi points out that the decisions of the next Government may modify the regulatory environment of specific sectors. In banking, the focus is on mergers, the specific tax, and state participation in CaixaBank. In the economy in general, housing and immigration appear as two of the issues with the greatest capacity to condition medium-term prospects.

Immigration thus occupies a singular position in both analyses. It is not just a matter that could mark the political debate of the campaign: in the case of JP Morgan, the arrival of the active population is part of the factors that are driving growth. The investment bank also warns that this engine is combined with investment from European funds to sustain activity. 

More key points, information and questions with FREN

AI-GENERATED CONTENT

What is the parliamentary process for forming a Government after general elections in Spain?

In Spain, the formation of a Government after general elections is mainly regulated by the Constitution (art. 99) and the Rules of the Congress and the Senate. It is a parliamentary process, although with the intervention of the King, which can be summarized in several clearly differentiated phases.

1. Proclamation of results and constitution of the Cortes Generales
  • After the elections, the Central Electoral Board proclaims the definitive results and assigns the seats in the Congress and the Senate.
  • The constitutive session of both Chambers is convened, in which:
    • The deputies and senators take possession of their seats.
    • The Board of each Chamber (Presidency, Vice Presidencies, and Secretariats) is elected by internal vote.
  • With the constitution of the Congress, the body that must grant or deny confidence to the future president of the Government is configured.
2. King's round of consultations with the parties
  • With the Cortes already constituted, the King opens a round of consultations with the representatives designated by the parties with parliamentary representation, usually starting with the smaller groups and ending with the larger ones.
  • The objective of these consultations is to check which candidate can gather the most support to obtain the confidence of the Congress.
  • The consultations do not have a rigid schedule in the Constitution, but they are usually held within a relatively short period after the constitution of the Chamber.
3. Proposal of candidate for the Presidency of the Government
  • After the consultations, the King proposes a candidate for the Presidency of the Government to the Congress of Deputies.
  • That candidate is usually the leader of the party with the best chances of achieving a majority (whether an absolute majority on their own, a coalition, or external support).
  • The proposal is communicated to the Presidency of the Congress, which convenes the investiture session.
4. Investiture session in the Congress
  • The Presidency of the Congress sets the date and agenda of the investiture session.
  • Development of the debate:
    • The candidate presents their Government program and the general lines of their political action without time limit.
    • Then the parliamentary groups intervene, following an established order (usually from largest to smallest representation). Each group can debate with the candidate through turns of reply and rejoinder.
  • Once the debate is finished, the investiture vote takes place, which is always nominal and public (each deputy orally expresses their vote).
5. Necessary majorities and possible scenarios
  • First vote: the candidate needs an absolute majority of the Congress (176 out of 350 deputies).
  • Second vote: if not obtained, a new vote is held 48 hours later. In this second vote, a simple majority suffices (more yes than no votes, excluding abstentions).
  • If the candidate obtains confidence, the King formally appoints them president of the Government by royal decree, and the appointment of ministers proceeds.
  • If not obtained, the King can open a new round of consultations and propose another candidate (or the same one, if it is considered that the balance of support can change).
6. Maximum period before new elections
  • The Constitution establishes a period of two months from the first investiture vote:
    • If within those two months no candidate has obtained the confidence of the Congress, the Cortes are automatically dissolved.
    • The King must call new general elections, which are held 47 days after the call.
  • During this period without an invested president, the outgoing Government remains in office, with limited powers.
7. Appointment of the Government and taking office
  • Once the president is elected by the Congress:
    • The King signs the royal decree of appointment, which is published in the Official State Gazette (BOE).
    • The president takes office and proposes to the King the appointment of the ministers, also by royal decrees.
    • The new Government holds its first Council of Ministers and fully assumes its functions.

In summary, the formation of the Government after general elections in Spain is a parliamentary process centered on the Congress of Deputies, where the key is obtaining a sufficient majority in the investiture, with a relevant but formal role of the King and a clear time limit: if there is no invested president within two months from the first vote, the country returns to the polls.

Can you explain in more detail how the investiture session in the Congress develops, turn by turn? What differences are there between a caretaker Government and a fully invested Government in terms of their powers? How does the process change when the election result requires forming a coalition Government?

What are the main powers of the president of the Government according to the Spanish Constitution?

The president of the Government is the central figure of the executive power in Spain. Their powers are mainly defined in articles 97 to 100 of the 1978 Spanish Constitution and are complemented by other provisions of the constitutional text. Broadly speaking, the president directs the Government's action, coordinates the ministers, sets the general political orientation, and maintains political responsibility before the Cortes Generales.

1. Direction of the Government's action

The core power of the president is to direct the Government's action. This means setting the broad lines of general policy, deciding priorities, setting the agenda, and ensuring the coherence of the Executive as a whole. The Government, as a collegiate body, is responsible for internal and external policy, civil and military administration, and the defense of the State, but it is the president who leads and coordinates this action.

In practical terms, this translates into the president:

  • Determines the Government's political objectives and programs.
  • Promotes bills and major regulatory initiatives that the Executive sends to the Cortes.
  • Coordinates the policies of the different ministries to avoid contradictions and overlaps.
2. Coordination and hierarchy over the ministers

The Constitution establishes that the president coordinates the functions of the other members of the Government. Although each minister directs their department with functional autonomy, all are subject to the general orientation set by the president.

From this position derive several essential faculties:

  • Propose to the King the appointment and dismissal of the vice presidents and ministers.
  • Reorganize the Government's structure (creation, suppression, or modification of ministries and vice presidencies, within the legal framework).
  • Resolve conflicts between ministries and decide ultimately on internal disagreements.

In short, the president acts as the political head of the ministerial team and guarantor of the Executive's unity of action.

3. Relationship with the King and the appointment of the Government

The president occupies a key place in the articulation between the Crown and the Government. Formally, they are appointed by the King, after investiture by the Congress of Deputies, but once in office, the president:

  • Proposes to the King the list of vice presidents and ministers that will make up the Government.
  • Submits to royal sanction the laws approved by the Cortes that the King must then promulgate.
  • Signs, together with the King, the acts that constitutionally require countersignature, which implies assuming political responsibility for them.
4. Relationship with the Cortes Generales and political responsibility

The president is subject to a regime of political responsibility before the Congress of Deputies. Their powers are always understood within this parliamentary logic:

  • Must obtain the confidence of the Congress through the investiture debate.
  • Can raise a vote of confidence to reconfirm their parliamentary support.
  • Can be removed through a constructive vote of no confidence, which must propose another candidate for the presidency.
  • Politically answers for the Government's action in control sessions, appearances, and parliamentary debates.

Additionally, they politically represent the Government before the Cortes, presenting programs, management reports, and strategic orientations.

5. Power of dissolution and calling elections

One of the president's most relevant functions is to propose the dissolution of the Congress, the Senate, or both Chambers and the calling of general elections, which the King carries out at their proposal. This power gives the president a key tool for managing the political calendar and resolving institutional deadlocks, with the limits set by the Constitution itself (for example, dissolution is not allowed during a state of exception or in certain periods).

6. Direction of foreign policy and defense

Although the Constitution attributes foreign policy and defense to the Government as a whole, the president, as director of its action, has special responsibility in these matters:

  • Heads the representation of the State abroad at the political-governmental level.
  • Defines, together with the competent minister, the main lines of foreign and European policy.
  • Exercises political direction over national defense, in coordination with the Minister of Defense, respecting the King's powers as Head of State.
7. Other relevant powers

Alongside the above, the president of the Government:

  • Orders the publication of Government norms and provisions.
  • Can issue political guidelines and circulars to guide the action of the General State Administration.
  • Is the central coordination figure in crisis situations (emergencies, states of alarm, etc.), as the highest political authority of the Executive.

Overall, the Constitution configures the president of the Government as the apex of executive power, ultimate responsible for the country's political orientation and main interlocutor both before the Cortes Generales and before the King and the international community.

What legal requirements must be met for a bank to carry out a merger in the Spanish banking sector?

In Spain, the merger of two banks is not just a corporate operation: it is subject to a double (or triple) simultaneous control: corporate-commercial, prudential (banking), and competition/stock market. Broadly speaking, for a banking merger to be valid, three major blocks of requirements must be met.

1. Basic regulatory framework

According to our database, which collects official records and specialized press, the main framework is:

  • Prudential banking law: Law 10/2014, on the organization, supervision, and solvency of credit institutions, and its development by Royal Decree 84/2015 and the Bank of Spain's circulars, plus the EU Capital Requirements Directive (CRD) and Capital Requirements Regulation (CRR).
  • Recovery and resolution: Law 11/2015, on recovery and resolution of credit institutions, along with the Single Resolution Mechanism (Regulation (EU) 806/2014).
  • European supervision: regulation of the Single Supervisory Mechanism (Regulation (EU) 1024/2013), which grants the ECB the authorization and prudential evaluation of significant entities.
  • Corporate: regime of mergers of capital companies (currently integrated in the consolidated text of the Capital Companies Act and complementary rules on structural modifications).
  • Competition: Law 15/2007, on Defense of Competition, and the EU merger regulation when European thresholds are met.
  • Stock market and takeovers (if there is a share exchange or listed companies): consolidated text of the Securities Market Law and Royal Decree 1066/2007 on takeovers, as well as recent royal decrees on admission to trading and market infrastructures.

2. Necessary authorizations

In a typical banking merger, at least the following authorizations or non-oppositions must concur:

  • Prudential supervisor:
    • For significant entities under the Single Supervisory Mechanism, the ECB evaluates the operation from a prudential perspective (solvency, risks, suitability of administrators, business model).
    • The Bank of Spain acts as the national competent authority and channels much of the analysis and interlocution.
  • Competition authority:
    • In Spain, the CNMC analyzes whether the merger significantly reduces competition in the affected banking markets and can impose conditions (divestments, quota limits, etc.).
    • If certain turnover thresholds in the EU are exceeded, the concentration may also be examined by the European Commission under the merger regulation.
  • Stock market:
    • If the operation is structured through a prior takeover bid (OPA), the CNMV must authorize the offer, the prospectus and its modification, and ensure that shareholders have sufficient and truthful information.
  • Government and Ministry of Economy:
    • Law 10/2014 foresees that the merger of credit institutions requires a government authorization when it significantly affects the financial system; the Government decides once the reports from the Bank of Spain, ECB, and other supervisors are issued.
    • This additional governmental intervention power is precisely what the European Commission is questioning and wants to limit to purely prudential criteria.
  • Shareholders' meetings of the entities involved, which must approve the merger project.

3. Prudential and solvency requirements

Besides the form, the prudential authority verifies that the resulting entity:

  • Maintains regulatory capital ratios (CET1, Tier 1, total) above the Pillar 1 minimums, the macroprudential buffers set by the Bank of Spain, and the Pillar 2 requirements set by the ECB.
  • Complies with MREL requirements (own funds and eligible liabilities to absorb losses) and other resolution demands of Law 11/2015 and the Single Resolution Mechanism.
  • Has adequate governance:
    • Suitability and honorability of administrators and executives.
    • Organizational structure and risk management systems consistent with the new size and complexity.
  • Demonstrates in its business plan that the merger is viable, with analysis of synergies, integration costs, and financial projections.
  • Does not generate disproportionate risks for national or eurozone financial stability.

4. Corporate merger procedure

On the commercial level, banks, as public limited companies, follow the general merger regime:

  • Preparation of a common merger project approved by the boards of directors.
  • Report of administrators explaining reasons and effects of the operation, and, when appropriate, report of an independent expert.
  • Publication of the project and making it available to partners and creditors.
  • Rights of information and, if applicable, opposition of creditors within the deadlines provided by law.
  • Agreement of the general meeting in each entity.
  • Granting of the merger deed and registration in the Mercantile Registry; only then does the merger have full effects (block transfer of assets, universal succession, etc.).

In summary, a banking merger in Spain requires complying with the corporate procedure of any public limited company, but also passing a dense prudential filter (Bank of Spain/ECB), resolution (Law 11/2015), competition (CNMC and, if applicable, European Commission), stock market if there is a takeover bid, and, currently, a final Government decision in the cases foreseen by Law 10/2014, although this last point is under review following recent European regulations.

Could you explain in more detail the specific role the European Central Bank plays in approving a Spanish banking merger? What practical differences are there between a national banking merger and a cross-border one within the European Union? Could you give me as an example the case of CaixaBank–Bankia or the attempted BBVA–Sabadell merger and what specific requirements they had to overcome?

Play

Test your knowledge with FREN!

How much do you know about this topic? Answer the following 3 questions.

What is the immediate impact that Citi and JP Morgan foresee on the Spanish economy due to the early elections?

Question 1 of 3

What element does JP Morgan highlight as key for Spain's economic growth?

Question 2 of 3

According to Citi, what could change if the Government is led by the PP regarding the banking sector?

Question 3 of 3